
Aspora Is Making Cross-Border Banking Simpler for Indians Abroad
Why Cross-Border Banking Remains Complicated for Indians Abroad?
For millions of Indians living overseas, managing money across borders is a regular part of life. Professionals send earnings home to support their families, contribute to property purchases, invest in India and maintain financial relationships with their home country. Yet moving money internationally can involve unfavourable exchange rates, transfer fees, processing delays and uncertainty about the final amount a recipient will receive.
Managing savings and investments in India can introduce further complications, particularly when non-resident Indians need specialised accounts and must navigate different regulatory systems. Traditional banks offer international transfers and NRI banking services, but their processes can be difficult to navigate, while dedicated remittance providers may differ considerably in pricing, speed and transparency. These challenges create an opportunity for fintech companies that can simplify the experience through digital platforms.
Aspora, founded by Parth Garg in 2022, is targeting this problem by building financial services for Indians living abroad. The company began with cross-border transfers and has since outlined a broader ambition to connect diaspora communities with the financial infrastructure they need across countries. Backed by investors including Sequoia Capital, Greylock Partners, Hummingbird Ventures, Quantum Light, Y Combinator, Soma Capital and Global Founders Capital, Aspora has attracted significant investor interest in the opportunity.
In its September 2025 funding announcement, the company said it had raised $93 million across three funding rounds over the preceding six months. At that point, Aspora reported that more than 250,000 non-resident Indians were sending money through its platform and that it had processed over $2 billion in transfer volume. These figures illustrate the demand for a more convenient way to manage international money movements, although they represent company-reported milestones rather than independent measures of market share.
How Aspora Is Simplifying International Money Transfers?
Aspora’s core proposition is straightforward: make sending money home easier to understand, faster to arrange and more transparent in cost. Its digital platform allows customers in supported countries to initiate transfers to India without relying entirely on conventional bank-transfer processes. One of its central selling points is exchange-rate transparency.
Aspora promotes transfers at Google exchange rates, helping users compare the rate they receive with a familiar reference point. The company also emphasises the absence of hidden fees, although customers should check the applicable terms and transfer conditions for their country and transaction. Its UK service, for example, presents live exchange-rate information and promotes secure transfers, digital onboarding and round-the-clock customer support. Behind the user experience is a financial infrastructure that depends on regulated entities and payment partners operating across different jurisdictions. Aspora does not use a single regulatory arrangement for every market.
Its UK operating entity, Real Transfer Limited, is authorised by the Financial Conduct Authority as a payment institution for regulated payment activities, while its Canadian and US operations have their own registration and partnership arrangements. This structure is important because cross-border payments require compliance with local rules, identity verification and safeguards for handling funds. Aspora’s opportunity is to make these complicated processes feel simpler to customers without removing the regulatory checks required to move money safely.
The company also reports that its customers have saved millions of dollars in fees compared with traditional remittance alternatives. Such savings depend on the transfer amount, exchange rate, provider fees and the comparison being made, but lower costs can make a meaningful difference for people who send money regularly. For users, the strongest proposition is the combination of a familiar digital interface, transparent pricing and a service designed around the needs of people living away from home.
Beyond Remittances: Aspora’s Vision for Cross-Border Finance
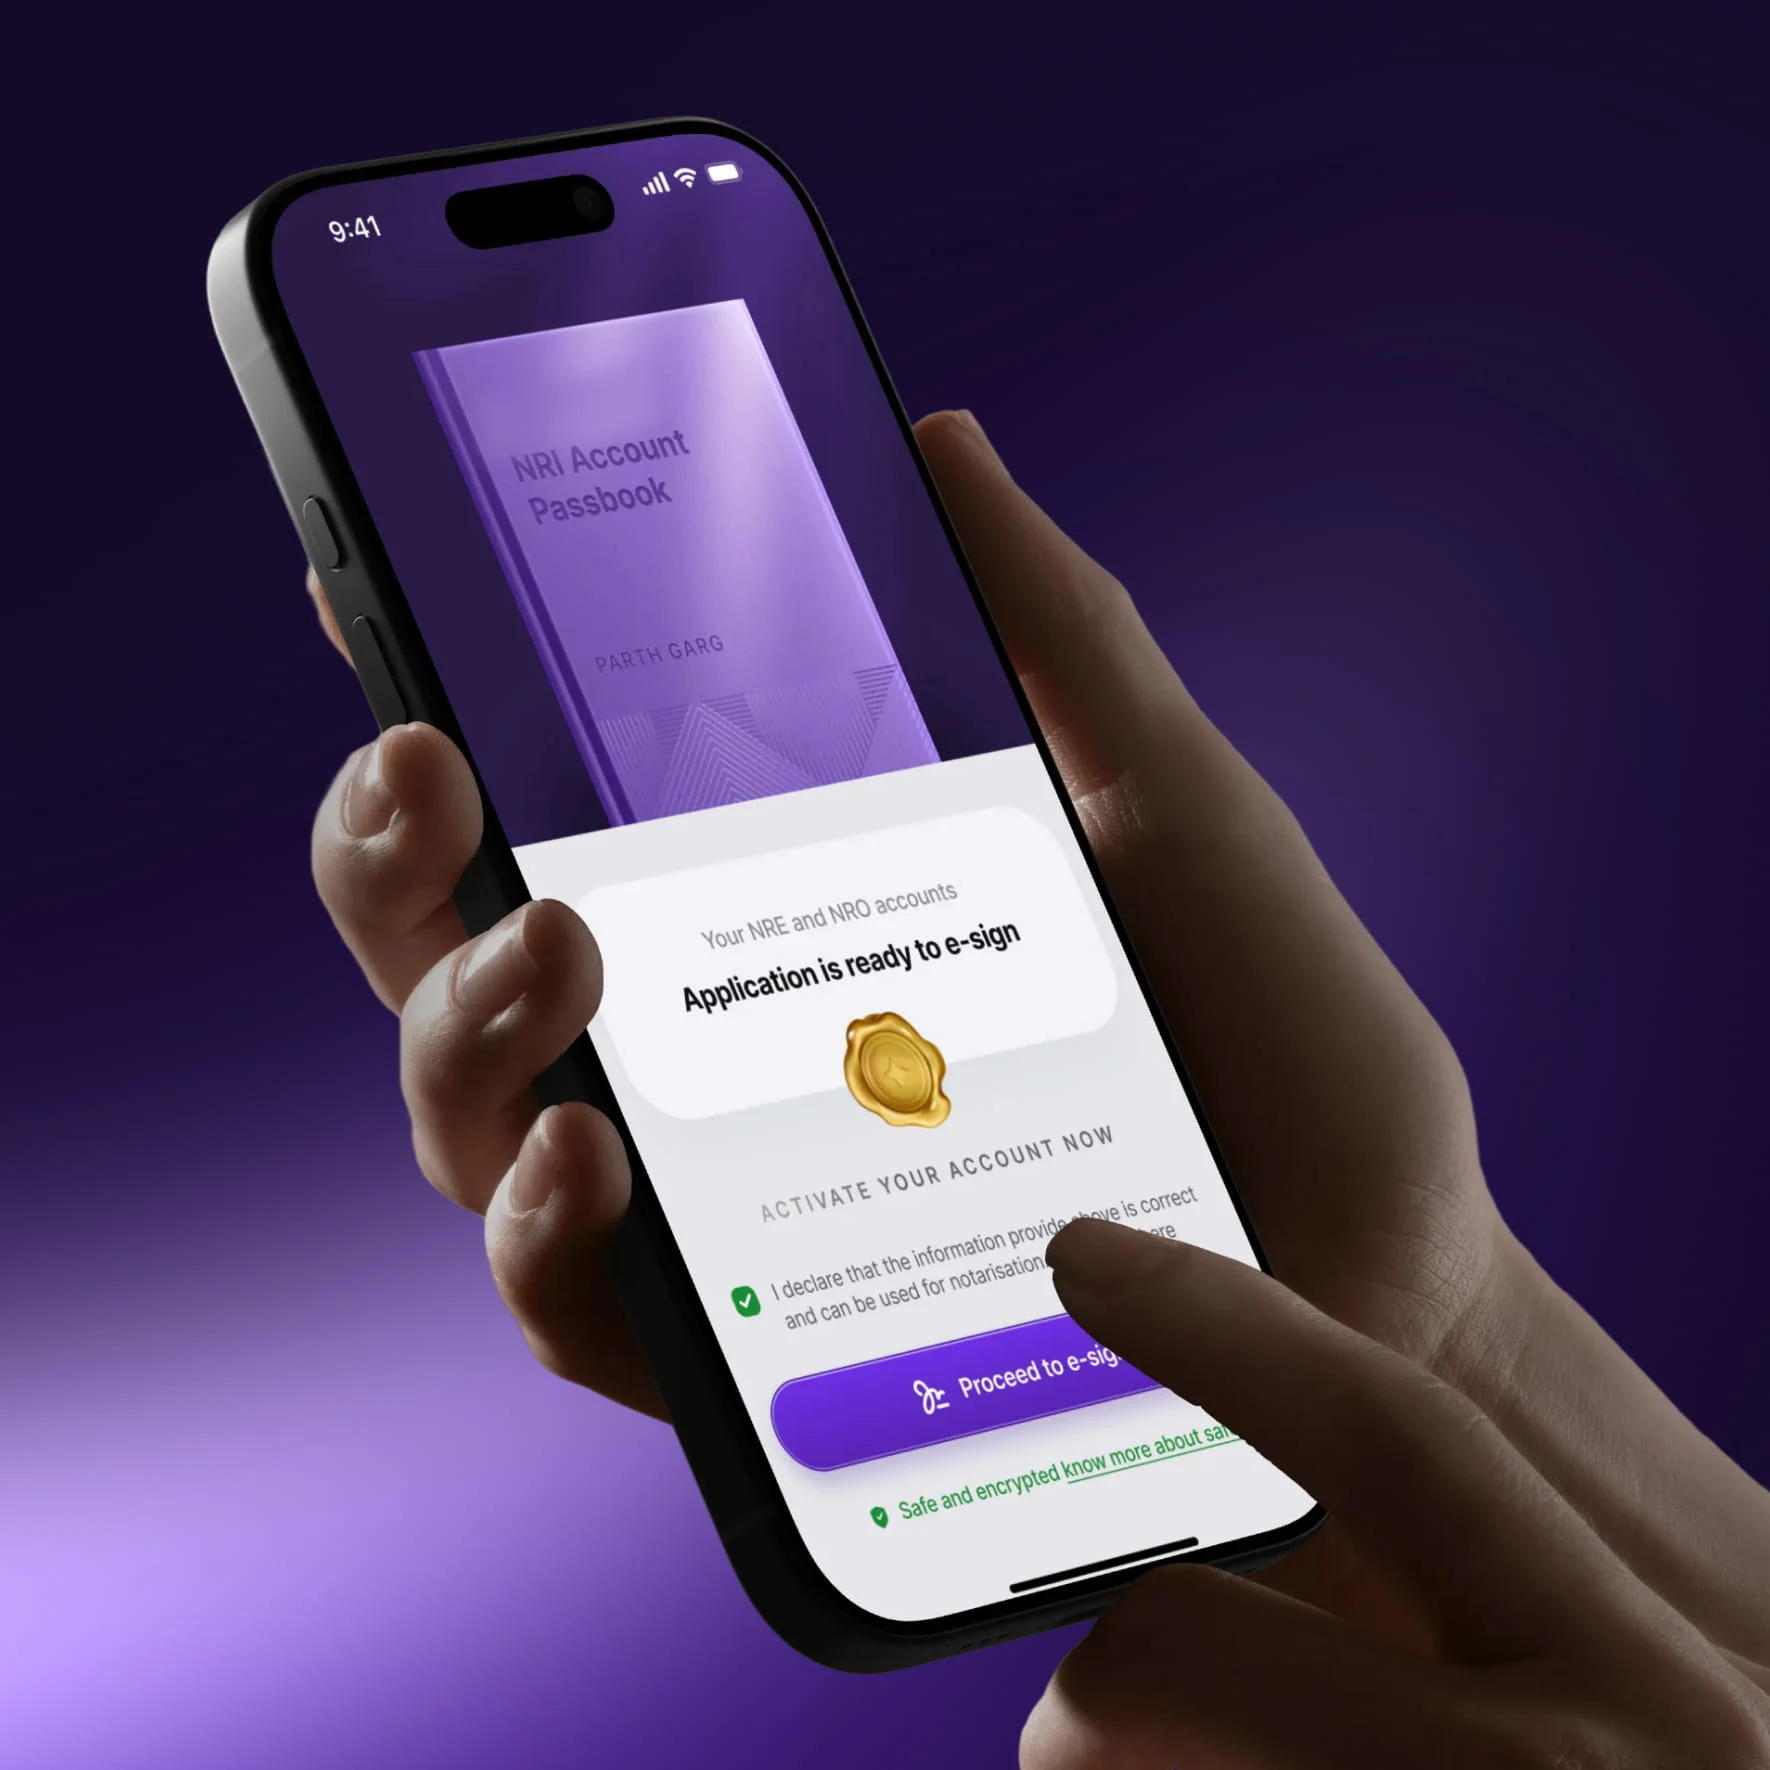
Aspora’s longer-term ambition extends beyond helping customers send money to India. Its NRI banking initiative is designed to help eligible non-resident Indians access NRE and NRO accounts through the platform, with advertised savings and fixed-deposit rates subject to the relevant bank’s terms and approval. These accounts are provided by regulated banking partners rather than by Aspora itself.
The distinction matters: Aspora facilitates the application and customer experience, while the partner bank is responsible for opening and maintaining the account. The company has also introduced an investment proposition through Aspora Gold in the UK. Customers can buy and sell allocated 24-karat gold through the app, with the gold provided by regulated UK partner Goldwise and held in Brink’s vaults in the customer’s name. The product allows eligible users to start investing from £10, although gold prices can fall as well as rise and investors may receive less than they put in.
Together, these offerings point towards a platform that could help diaspora customers transfer money, maintain savings and access selected investments through one digital experience. The challenge will be delivering that wider vision across countries with different banking regulations, tax rules, currencies and consumer-protection requirements.
Aspora must also earn trust in a category where customers are transferring money they may need for family expenses, housing or long-term savings. Clear pricing, reliable payment execution, responsive customer support and transparent explanations of who holds and protects funds will remain essential as its product range expands. Competition from banks, remittance specialists and other fintech platforms will put pressure on fees and service quality, while expansion into additional financial products brings new operational and regulatory responsibilities.
Aspora’s progress will therefore depend on more than user growth or the number of services it launches. Its larger opportunity is to build a dependable financial connection between Indians abroad and their home country, reducing the friction involved in managing money across borders. If it can maintain that trust while expanding responsibly, Aspora could become a useful financial platform for a global Indian community whose financial lives increasingly span multiple countries.